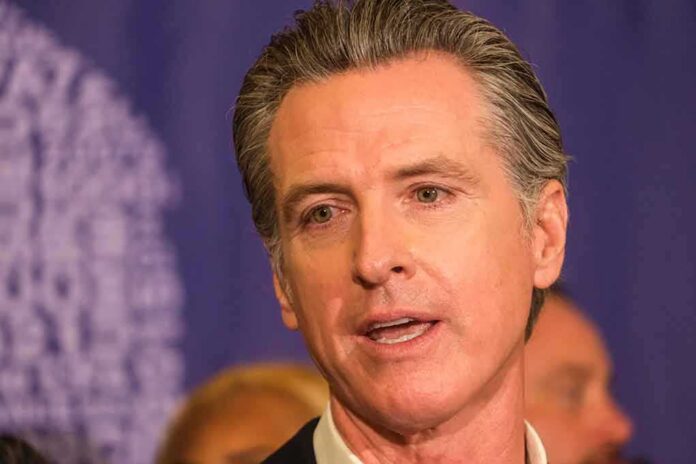
Prediction markets didn’t just drift on Gavin Newsom after the midterms; they repriced him—reducing his implied chances to a single-digit snapshot that reset the 2028 conversation and elevated rival Democrats in his lane.
At a Glance
- Multiple trackers logged Newsom around 7% in the days after the midterms, described as a lifetime or record low on at least one widely watched market.
- The drop coincided with a shift toward alternative Democratic contenders such as Jon Ossoff and Alexandria Ocasio-Cortez in contemporaneous market boards.
- Trading activity was heavy, with reported tens of millions of dollars tied to these contracts, underscoring that this was broad repricing rather than a stray quote.
- Cross-platform prices diverged by contract and timestamp; single-number “odds” reflect market definitions and timing, not a universal forecast.
What the markets actually moved: a sharp post-midterm repricing
In the immediate aftermath of the midterms, several market snapshots placed Gavin Newsom’s 2028 prospects in the single digits. One tracker recorded a 7% implied probability on a presidential-winner contract and labeled it a lifetime low, and press coverage the same weekend described a 7% print as a record low for Newsom. This was not a glacial slide. Independent logs show a step-down over roughly a week—from about 12% to 7%—across thousands of intraday price points accumulated since midsummer, the statistical footprint you see when many traders react, not when one whale skews a thin book.
The repricing was not limited to Newsom in isolation; boards simultaneously reweighted other Democrats. A widely circulated snapshot put Jon Ossoff and Alexandria Ocasio-Cortez ahead of Newsom on key markets immediately following the midterm vote counts, with Ossoff cresting in the high-20s and Ocasio-Cortez in the teens in at least one display of nomination or winner boards. Those relative placements matter because they reflect a portfolio rotation inside the same information ecosystem rather than a one-off markdown of a single name.
Volume, liquidity, and why this wasn’t a stray tick
Price alone doesn’t tell you much without liquidity. Here, reported turnover tied to Newsom’s 2028 prospects exceeded $28 million around the midterm window, nested within far larger election-market activity; that order flow is consistent with a meaningful repricing rather than a screen artifact. The midterms themselves were a gravitational event for prediction markets, with election trading reaching into the billions across platforms—a scale that concentrates attention, narrows spreads, and hardens prices into consensus snapshots more than in routine periods. In short: lots of eyes, lots of orders, and enough depth that a 5-point slide in a week signals a collective reassessment rather than idle noise.
None of this turns markets into oracles. But when turnover is high and books are two-sided, single-digit prints carry more informational content than they would in a sleepy off-peak market. They reflect changed expectations.
Contract definitions: nomination versus presidency, and why the number varies
If you track “Newsom 7%” across the internet, you will encounter mismatched denominators. Some markets price “Will Newsom win the presidency?” Others ask “Will Newsom win the Democratic nomination?” Still others translate sportsbook fractional odds or list cross-platform averages. Around the same window, one source showed Newsom near 10–11% on a nomination frame, another at 10.5% on a different platform’s construction, while a sportsbook line translated to a mid-teens implied chance—evidence of definitional and timestamp divergence, not contradiction.
Two implications follow. First, a single percentage cannot function as a universal probability; it is a contract-specific snapshot. Second, “record low” is meaningful only relative to the exact market’s own history and resolution language. The strongest post-midterm evidence for a lifetime low applies to a presidential-winner contract where the 7% print is recorded in the series history; nomination boards at that moment showed higher, non-record numbers.
Mechanism and narrative: how the midterms filtered into prices
Prediction markets digest information like any other security: traders update a prior, place orders, and prices move to clear. During a national event such as the midterms, three streams flow into those priors simultaneously—hard returns, elite signals (who campaigned effectively, who banked goodwill), and media framing that shapes perceived electability. In this case, the immediate effect was rotational: competing Democrats gained share on the boards while Newsom’s price sagged. Press snapshots show Ossoff and Ocasio-Cortez surging relative to Newsom right after the counts, a tell that traders were reassessing the pecking order inside the party for 2028 rather than simply marking down Democrats wholesale.
Causation is a higher bar than correlation. The evidence here is clean on sequence and magnitude but does not isolate a specific race call or speech as the trigger; prediction-market coverage itself cautions that prices are expectations, not polling or adjudicated history. That caveat is healthy, and it does not blunt the central fact: the post-midterm window produced a durable-looking repricing with breadth and volume behind it.
How much weight to put on markets: calibrated, growing, and fallible
For two decades, election markets have competed with polls as “nowcasts” of political reality. Their track record is mixed in the particulars but often well calibrated in the aggregate—meaning that contracts priced at 60% tend to resolve affirmative about six times in ten over many events—especially when measured across a broad panel of contests. The sector has also professionalized and scaled: by the midterms, platforms reported eye-popping volumes and regulatory visibility, with billions traded and formal oversight on at least one major U.S. venue.
Yet markets miss. Cross-national election cycles and primary battles produce enough high-profile errors to remind observers that price is expectation, not truth. Analysts and reporters covering midterm-week boards explicitly flagged that fallibility while still using the prices as a clean read of sentiment in the moment. The right way to read a 7% print, then, is as a consensus expectation under uncertainty—responsive, often disciplined by money on the line, but contingent.
Democrats swept the midterms.
Gavin Newsom's 2028 odds just hit an all-time low: 7%.
The whole party caught a wave.
Newsom caught the undertow. https://t.co/DQEa4J6KFJ— Common Sense Report (@Fernand08130933) November 8, 2026
What this means for Newsom and his competitors
Practically, single-digit winner odds compress strategic oxygen. Donors and operatives watch the same boards that journalists cite; when a candidate drifts down while rivals gain, it becomes harder to project inevitability or to deter others from staffing up. The post-midterm boards pointed to a more competitive Democratic field in which Ossoff and Ocasio-Cortez, among others, commanded trader attention alongside stalwarts like Kamala Harris and Pete Buttigieg in various snapshots. That doesn’t foreclose a Newsom rebound—market histories are littered with recoveries—but it does set the baseline he must beat.
How to track this story without getting spun by a single number
Focus on like-for-like comparisons: the same contract, the same timestamp window, and the same platform when judging trend. Watch volume and spread—tight books with heavy turnover speak louder than sporadic trades. Distinguish nomination from presidency pricing. And when headlines tout “record lows,” check whether they refer to the specific market’s own time series. In the days after the midterms, those checks yield a clear bottom line: Gavin Newsom’s implied presidential chances printed around 7% on at least one liquid winner market, while competitors climbed, with eight-figure trading activity anchoring the move. That is a real repricing—and a useful map of where the 2028 conversation turned next.
Sources:
2028tracker.com, polymarkettrader.com, nypost.com, kresmion.com, kalshi.com, dnyuz.com, predictmatters.com, vegasodds.com, stateline.org, cbc.ca, reuters.com