Where you live can turn the loss of a spouse into a solvency crisis: the same death that is emotionally shattering in Omaha can be financially devastating in Irvine, because local prices, taxes, wages, and housing dynamics either cushion the income shock—or magnify it.
At a Glance
- Ethos modeled first-year financial exposure after a spouse’s death across 100 U.S. metro and housing markets; Irvine, Fresno, Los Angeles, and San Francisco sit among the most punishing environments.
- The driver isn’t grief spending; it’s structural math—high housing costs, childcare or solo-parent expenses, and income loss colliding with local price levels.
- Widowhood consistently reduces household income and living standards nationwide; local conditions determine whether that drop becomes outright instability.
- Planning levers exist—survivor benefits, term life coverage sized to local costs, debt and housing choices—that materially change the first-year trajectory.
What the ranking actually measures—and why California looms large
Ethos analyzed 100 U.S. markets to estimate how far a surviving spouse’s income would stretch in year one after a death, incorporating cost of living, earnings, housing, and funeral costs. In that model, Irvine ranks as the most financially vulnerable place to lose a spouse, with Fresno, Los Angeles, and San Francisco also among the hardest-hit markets. The through-line is intuitive: when fixed local costs are high and a household suddenly drops from two incomes to one (or from one-and-a-half to one), affordability can collapse with startling speed. Secondary coverage summarized the finding in plain terms—California dominates the “worst places to be widowed” list because its most expensive markets compound an already severe income shock.
This is not a judgment about culture or community; it is arithmetic. California’s marquee metros pair high rents or mortgages with steep childcare and transportation costs. Lose a paycheck and the budget gap that was survivable in a cheaper market can become untenable on the coast. Funeral prices are a rounding error compared with housing, but they arrive immediately and in cash-like terms, adding stress right when liquidity is tight.
The mechanism of the first-year shock
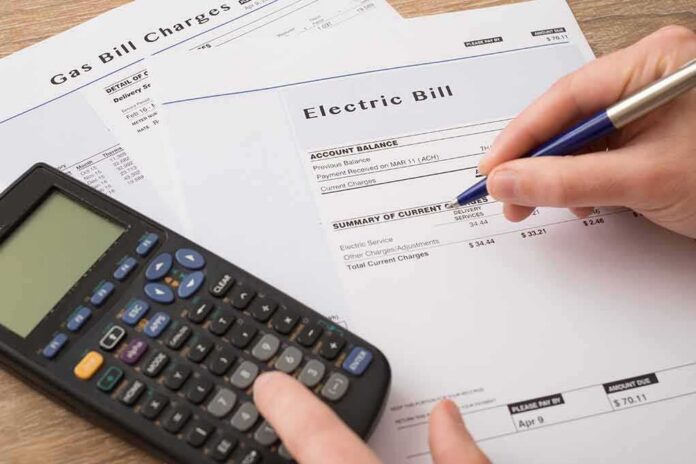
Household finance during widowhood turns on three simultaneous shifts. First, recurring income falls—wages, business income, and often a portion of retirement benefits disappear. Second, several costs rise or stay fixed: housing payments do not halve because a spouse dies; solo parents may now need paid childcare; and health insurance can become more expensive if the deceased carried the employer plan. Third, one-time expenses arrive fast: funeral and burial or cremation, estate administration, travel for family, and sometimes an urgent move if housing is no longer affordable. In high-cost metros, the combination is unforgiving because fixed costs dominate the budget, leaving little room to absorb lost income without immediate deleveraging or outside support.
Models like Ethos’s are not destiny—they do not know your exact wage, debt, or insurance coverage—but they are reliable at one thing: highlighting where a standard household is most exposed when one paycheck disappears. As a screening tool, they identify markets where emergency liquidity and pre-loss planning matter most.
How this squares with decades of research on widowhood and poverty
Independent academic and policy studies have long documented the financial consequences of spousal death. National analyses find that living standards fall sharply after widowhood—on the order of an 18 percent decline on average—and that a meaningful share of women who were above the poverty line before widowhood fall below it afterward. Health and Retirement Study evidence similarly shows substantial short-run losses in income and wealth for recent widows, even as labor-force participation and public benefits mitigate some of the damage over time.
The Chicago Fed’s synthesis is blunt about the early period: household income drops materially and financial insolvency rates roughly double in the aftermath; survivor benefits at age 60 help, but they arrive late in the life cycle and do not address younger families or the first-year cash crunch. In other words, the city-by-city ranking and the national literature tell the same story at different resolutions. The macro evidence establishes the shock; the local analysis shows where that shock is hardest to absorb.
What “expensive” means in practice: housing, childcare, and taxes
In the California metros that cluster near the top of Ethos’s vulnerability list, housing is the fulcrum. Mortgages and rents set a high monthly floor; property taxes, HOA dues, and insurance layer on top. When a household loses one income earner, the debt-to-income ratio can jump overnight from healthy to precarious. Add paid childcare—especially for a surviving parent with a school-age child—and the budget can break. Even well-paid survivors can find that the marginal tax and benefit interactions of their new filing status reduce take-home pay or eligibility for means-tested supports just when they need help the most.
By contrast, in lower-cost metros with shorter commutes, cheaper housing, and more flexible childcare ecosystems—often in the Midwest or South—the same loss is painful but less likely to trigger an immediate move or a debt spiral. The difference is not that grief is cheaper; it is that fixed obligations are smaller.
Planning levers that change the first-year math
Four decisions, made before loss, show outsized power in high-cost markets. First, right-size term life insurance to local fixed costs—mortgage balance, at least one year of housing and childcare, and any high-interest debts. Insurers commonly illustrate funeral expenses in the $7,000–$12,000 range; useful for framing, but the real hedge is replacing lost after-tax income for a defined period so the survivor is not forced into a distressed sale or a hasty move. Second, align Social Security strategy: a primary earner who claims early permanently reduces the survivor benefit, which can materially increase widowhood poverty risk; coordinated claiming maximizes the floor under future income.
Third, structure housing with downside protection: avoid mortgage terms that require dual incomes to qualify comfortably, keep an adequate cash reserve equal to several months of payments, and consider portable coverage that clears the mortgage on death. Fourth, clarify account titling, beneficiary designations, and durable powers so assets move quickly without probate delays. In the first year, liquidity beats theoretical net worth.
How to read a city ranking wisely
Location rankings are models; they are useful if you understand their inputs and limits. Ethos’s approach blends local income and price data to estimate first-year strain; it does not predict an individual survivor’s outcome. Households with strong balances, generous employer life coverage, or multigenerational support can thrive even in expensive markets. Others, carrying high leverage and no insurance, can struggle anywhere. But as a planning map, the list is signal-rich: if you live in Irvine, Los Angeles, San Francisco, or Fresno, the margin for error is thinner, and the value of pre-commitment—insurance, cash buffers, paperwork readiness—is higher.
The enduring lesson is not that California is unlivable for the bereaved; it is that structural costs determine how quickly a private tragedy can become a financial emergency. You cannot time grief. You can, however, de-risk it—especially where the math is least forgiving.
Sources:
nypost.com, ethos.com, moneygeek.com, longevity.stanford.edu, onlinelibrary.wiley.com, academic.oup.com