The fight over what to call the new generation of AI infrastructure is really a fight over what it is: not a building full of servers, but a multi-decade fusion of compute, power plants, high-voltage transmission, construction trades, and long-term financing. The terminology only matters if it maps to reality—and in Ohio, the facts show a campus-scale industrial system taking shape, even as open questions about costs, emissions, and risk allocation remain.
The Short Version
- OpenAI is promoting “compute campus” to reflect facilities that bundle compute, power generation and transmission, large-scale construction, and skilled employment—not just racks and chillers.
- Its Pike County, Ohio plan anchors the claim: up to roughly 8 gigawatts of IT capacity delivered in phases under a 20-year lease, with new power and grid buildout attached.
- Independent reporting clarifies capacity vs. consumption and confirms the project’s extraordinary scale; legal filings reveal a web of partners and guarantees.
- The rebrand itself doesn’t solve environmental, ratepayer, or community concerns; those hinge on verifiable power, water, emissions, and cost-sharing outcomes over time.
From “data centers” to “compute campuses”: what is actually changing
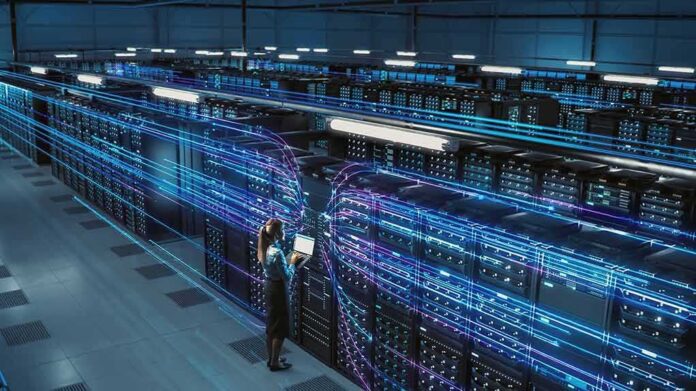
OpenAI’s rationale for the new label is straightforward: these sites now interlock computing with energy and construction at a scale that outgrows the mental model of a single boxy building. An OpenAI spokesperson put it bluntly—compute campuses better describe the infrastructure’s scale and role, spanning computing, energy systems, and skilled work. That framing is not hand-waving; it mirrors the structure of the Ohio project, where the landlord-developer will build, own, and operate facilities that OpenAI leases over two decades while capacity comes online in phases. The first tranche is pegged at roughly 800 megawatts by 2028, with later phases dependent on new generation and major grid additions.
Critically, the Ohio plan binds compute to energy development rather than treating electricity as a background utility input. OpenAI’s own materials tie later phases to new natural-gas plants, transmission lines, and related infrastructure—an energy program in its own right, not merely a power purchase arrangement. That is the operational logic behind “campus”: the servers are inseparable from the power system and the civil works that make them viable at this size.
Mechanics and partners: why this is a campus-scale industrial ecosystem
The development structure further supports the campus lens. SB Energy (a SoftBank affiliate) is the builder-owner-operator under a long lease; NVIDIA is identified as the exclusive AI-compute infrastructure provider and, crucially, as a credit-support provider for initial phases. OpenAI serves as the anchor customer for up to 8 gigawatts of IT capacity within a larger 10-gigawatt development. This is not a lone tech tenant retrofitting an anonymous warehouse; it is a consortium aligning compute deployment with bespoke energy assets, grid interconnections, and long-lived financial commitments—a campus by any reasonable industrial standard.
Local reporting has been valuable in translating headline figures. The oft-cited “8 gigawatts” pertains to IT capacity—the electrical capacity available to servers and specialized equipment—not necessarily continuous draw. Conflating the two exaggerates operational consumption and distorts comparisons; capacity is a design ceiling, not a 24/7 meter reading. That nuance rarely survives social-media discourse, but it matters for grid planning, emissions modeling, and rate-setting debates.
Where the evidence is strong—and where it is not
On definitional grounds, the evidence is strongest that “compute campus” accurately captures the integrated nature and scale of Ohio’s plan. OpenAI’s own description connects compute to new generation and transmission; contractual disclosures name multiple industrial partners across compute, development, and finance; and independent reporting confirms that capacity is unusually large and phased in over time. Those are concrete, attributable facts, not rebranding flourishes.
What the record does not show—yet—is that the term improves public acceptance or clarifies trade-offs for communities. There are no before-and-after attitude measures, no randomized message tests, and no demonstrated link between the label and local support. Meanwhile, media coverage has sometimes cast the shift as PR “newspeak,” a frame likely to harden skepticism rather than soften it, particularly in a climate where a majority of Americans tell pollsters they worry about the environmental footprint of data centers.
The unresolved questions that will decide community judgment
Renaming does not change physics, economics, or permitting. In Ohio and elsewhere, residents ask who pays for new energy and grid assets; how water, air, and noise will be managed; and what happens if the commercial assumptions unspool. The Ohio plan places early capacity in 2028 and ties later phases to new natural-gas generation and significant transmission build—each a venue for rate and siting disputes. Commentators have flagged that on-site or dedicated gas turbines concentrate emissions and noise locally, while large power demands can stress fuel and infrastructure supply chains, potentially nudging prices. These are not idle hypotheticals; they are standard friction points wherever hyperscale loads land.
The financial architecture also invites scrutiny. NVIDIA’s role as both exclusive infrastructure provider and credit backstop for early phases aligns incentives to build but raises questions about circular financing and who ultimately bears risk if demand, pricing, or model economics shift. Disclosures and analyses describe a residual value guarantee—capped but material—intended to assure landlords and lenders that capacity will be paid for or backstopped even if OpenAI falters; that is sophisticated and arguably necessary for timelines of this ambition, but it complicates simple narratives about who is on the hook in downside scenarios.
OpenAI may rebrand its data centers as "AI compute campuses," TechCrunch reports via Axios.
I live in those buildings. A new name doesn't change the power bill.
A campus should be earned by what the town gets back, on a public record.
What would you make them prove first? pic.twitter.com/Ypjvdia4hi
— ROBO (@ROBOFoundation) November 2, 2026
How to make “compute campus” more than a label
For the term to earn trust rather than suspicion, it must do explanatory work. That means pairing the label with verifiable, project-specific disclosures that map the campus’s physical and financial architecture to outcomes people care about. Three classes of evidence would go furthest. First, energy and environmental accounting that covers the whole system—generation mix over time, air permits and measured emissions, water balance including indirect water in fuel production and supply chains, and real load profiles rather than nameplate capacity. Second, economic delivery data—construction payrolls, prevailing-wage compliance, local procurement, permanent headcount by occupation and wage band, and net fiscal effects once abatements and incentives are included. Third, contract-level clarity—at least in summarized form—on how lease, power, and transmission costs are allocated, how ratepayer protections operate, and how default or curtailment risks are shared among counterparties.
Making those commitments legible will not satisfy everyone—some will oppose any new gas-fired generation or any large industrial site near homes or schools—but it will align language with mechanism. If “compute campus” means servers plus a power plant plus transmission plus long-lived capital and skilled trades, then show the mix, the milestones, and the measurements as they occur. Absent that, the term will be received as a euphemism, and critics will be right that a new label cannot mute the hum of a turbine or change a monthly bill.
Why the distinction still matters
Words shape governance. “Data center” evokes a zoned facility on a utility meter; “compute campus” evokes an industrial complex integrated with power and grid assets. The Ohio plan, as described and contracted, looks more like the latter than the former—an ecosystem whose constraints are as much energy, transmission, and construction lead times as they are semiconductors. That is the correct mental model for regulators, utilities, labor, and communities to evaluate. It is also the frame in which the hardest questions—emissions pathways during multi-year buildouts, cost allocation, and downside risk—must be answered. Labels do not settle those questions. Transparent, testable commitments do.
Sources:
businessinsider.com, africa.businessinsider.com, openai.com, dispatch.com, sullcrom.com, gizmodo.com, kirkland.com